CLAUSEDOCK GUIDES
How to Audit a 3PL Invoice: A Practical Checklist
A fulfillment invoice can add up correctly while using the wrong rate, quantity, or storage calculation. Checking the total is a useful starting point. Verifying the charges requires the records behind it.
To audit a 3PL invoice, reconcile the billing detail to the invoice, match each charge to the applicable pricing rule, verify the underlying activity, and document any difference with its source. Check existing credits before requesting a correction.
ClauseDock’s approach to 3PL billing review centers on that evidence: the billed amount, the expected amount where it can be established, and the records supporting each finding. This guide explains how to perform the review manually.
Start with one invoice and follow the steps below, or skip to the audit checklist.
What Does a 3PL Invoice Audit Check?
A third-party logistics invoice audit compares fulfillment charges with the applicable agreement and operational records.
For each charge, ask:
- What service or event triggered the fee?
- What quantity and billing unit should apply?
- Which rate and pricing rules were in effect?
- Has a related correction or credit already been posted?
The result should distinguish supported discrepancies from questions that need clarification.
For example, two charges referencing one order may relate to separate shipments. A storage difference may come from counting pallet positions at different points in the month. Understanding the rule behind the charge is what makes the review useful.
1. Gather the Invoice and Supporting Records
Collect the documents needed to reproduce the calculations.
| Record | Purpose |
|---|---|
| Invoice and transaction-level billing export | Identify charges, quantities, dates, and references |
| Contract and applicable rate card | Establish rates, billing units, inclusions, and exceptions |
| Amendments and approved pricing changes | Confirm which terms applied during the period |
| Order and shipment records | Verify fulfilled activity and split shipments |
| Receiving records | Support inbound quantities and receiving work |
| Storage reports | Verify occupied space and the counting method for 3PL storage fees |
| Return and special-service records | Support returns, kitting, labeling, and additional work |
| Credit notes and account adjustments | Identify corrections already processed |
Preserve the original files and review copies. Keep transaction IDs, original descriptions, and source row numbers.
If the invoice shows category totals only, request the supporting detail. A single “additional services” total may combine several activities with different pricing rules.
2. Establish the Applicable Pricing Rules
Confirm the rate-card version and effective dates before calculating expected charges.
An invoice issued in October may include September activity. Check whether your agreement applies pricing by service date, shipment date, billing date, or another defined event.
For each fee, record:
- Rate and currency.
- Billing unit.
- Included quantities or services.
- Volume tiers.
- Minimum charges.
- Rounding and proration rules.
- Effective dates.
- Applicable exceptions or approved additional work.
Public pricing pages help explain fee categories. Your account’s agreement establishes the rates to use.
For example, ShipBob’s pricing page lists receiving, warehousing, and picking, packing, and shipping among its standard categories, and states that quotes are customized.
Use the applicable account terms to calculate a discrepancy. If a rate or exception is missing, record the item as requiring clarification.
3. Reconcile the Billing Export to the Invoice
Make sure the export represents the invoice under review.
Confirm:
- Account and warehouse identifiers.
- Currency and billing period.
- Export filters.
- Positive charges and negative adjustments.
- Storage and other separately billed categories.
- Taxes, where applicable.
Compare the export total with the corresponding invoice charges.
Keep an invoice’s transaction charges separate from its opening balance, payments, and amount due. Those figures serve different purposes.
If totals differ, identify the missing or extra records before continuing. A filtered export, overlapping date range, or separately posted credit can change the result.
4. Match Each Charge to the Activity Behind It
Use the most specific operational reference available.
| Fee category | Useful supporting reference |
|---|---|
| Fulfillment | Order and shipment IDs |
| Receiving | Inbound delivery or receiving reference |
| Storage | Location report and billing period |
| Returns | Return and processing references |
| Special services | Work order, approval, or service record |
| Shipping adjustments | Shipment reference and adjustment detail |
Verify the event that triggers billing.
Orders placed and orders shipped are different quantities. One order may produce several shipments. A return may contain multiple items but carry a single processing charge, depending on the agreement.
For shipping, inspect the service level, destination, dimensions, actual weight, and applicable pricing basis. UPS explains dimensional weight as a calculation based on package volume and a divisor.
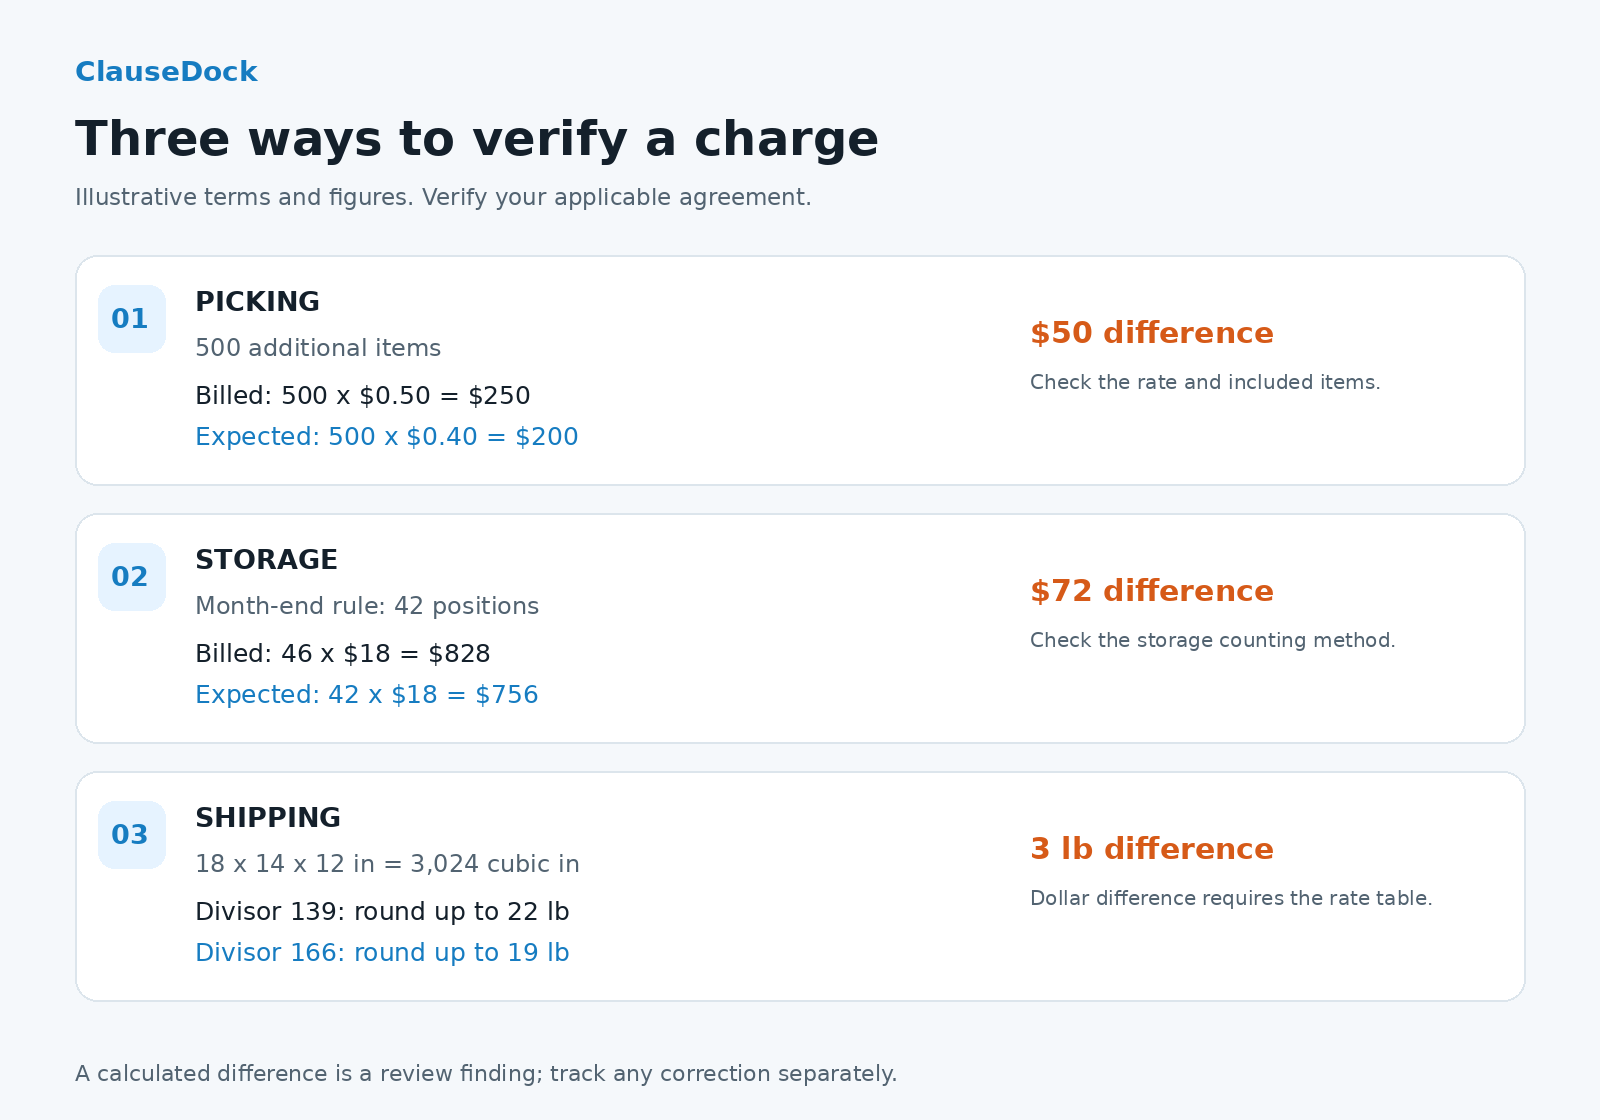
Worked example: dimensional weight
All numerical examples in this guide use fictional terms and records for illustration. They are not market rates or customer results.
Assume the applicable shipping agreement specifies:
- Package dimensions: 18 × 14 × 12 inches.
- Actual weight: 6 pounds.
- Dimensional divisor: 166.
- Fractional pounds rounded up.
- Billable weight is the greater of actual and dimensional weight, with no additional minimum applying.
Calculate package volume:
18 × 14 × 12 = 3,024 cubic inches
Calculate dimensional weight:
3,024 ÷ 166 = 18.22 pounds
Rounded up, the expected billable weight is 19 pounds.
The invoice shows 22 pounds. A divisor of 139 would produce:
3,024 ÷ 139 = 21.76 pounds → 22 pounds
That makes the divisor worth investigating. It does not establish which divisor the provider actually used.
The difference is 3 pounds of billable weight. Calculate a dollar discrepancy only after confirming the service, zone, applicable rate table, and any adjustments.
Divisors vary by rate type and agreement. Ask the provider to confirm its calculation and check whether corrected dimensions or another rule explains the charge.
5. Recalculate Charges With Sufficient Evidence
For a straightforward fee:
Expected charge = verified billable quantity × applicable rate
Then apply included quantities, tiers, minimums, proration, and rounding where relevant.
Worked example: additional-item picking fees
Assume the applicable rate card includes the first item in each order and charges $0.40 for each additional item.
Shipment records show:
| Order group | Orders | Items per order | Additional billable items |
|---|---|---|---|
| Single-item orders | 600 | 1 | 0 |
| Two-item orders | 300 | 2 | 300 |
| Three-item orders | 100 | 3 | 200 |
| Total | 1,000 | — | 500 |
Expected additional-item fees:
500 × $0.40 = $200
The invoice uses $0.50 per additional item:
500 × $0.50 = $250
Calculated difference:
$250 − $200 = $50
The quantity agrees with the shipment records; the rate differs from the stated pricing rule. Attach the relevant rate-card section and shipment detail to the finding.
For included picks, packaging, rate changes, tiers, and minimums, see our guide to 3PL fulfillment fees.
Worked example: storage counting method
Assume the applicable rate card specifies $18 per pallet position per month, calculated using the month-end count.
The storage report shows:
- Month-end count: 42 pallet positions.
- Peak count during the month: 46 pallet positions.
The invoice bills:
46 × $18 = $828
Expected storage charge:
42 × $18 = $756
Calculated difference:
$828 − $756 = $72
The key issue is the counting method. Under the stated month-end rule, the records support a $72 discrepancy.
If the agreement leaves the counting method unclear, request clarification before assigning an expected amount. Peak, average, daily, and month-end counts can produce different charges.
A useful lesson from the examples
The picking example has the correct quantity but a different rate. The storage example has the correct rate but a different quantity basis.
An audit therefore needs to verify both the price and the method used to calculate billable activity.
ClauseDock is preparing a self-service invoice review workspace. Customer uploads and checkout remain closed during release testing.
6. Investigate Possible Duplicate Charges
Compare more than the amount.
For a detailed method, including export overlap, credits, and overlapping fee names, see our guide to duplicate 3PL charges.
Review:
- Service description.
- Order, shipment, or receiving reference.
- Quantity and amount.
- Warehouse and service date.
- Transaction ID.
- Related reversals or credits.
First check whether repeated rows came from overlapping exports. Then determine whether the transactions represent separate services.
For example, two shipping charges against one order may correspond to two packages. Two similar receiving charges may cover distinct inbound deliveries.
Document what you found:
Two positive transactions reference the same shipment and service. The records reviewed show one service event and no offsetting credit. Provider clarification requested.
This gives the provider a specific issue to investigate.
7. Check Other Potential 3PL Billing Errors
The following are useful review checks. Each becomes a discrepancy only when the applicable terms and records support it.
| Potential issue | What to verify |
|---|---|
| An outdated rate applied after an amendment | Effective date and fee covered by the amendment |
| Per-item billing where the agreement specifies per order | Contractual unit and underlying activity |
| Included picks or packaging charged separately | Inclusion limits and relevant exceptions |
| Storage calculated using a different method | Peak, average, daily, or snapshot rule |
| Monthly minimum calculated incorrectly | Eligible fees and how the minimum interacts with activity charges |
| Additional-service fee without clear support | Rate-card provision, approval, and service record |
| Fuel surcharge using an unexpected percentage or base | Applicable schedule, date, and eligible charge base |
| A transaction appearing in multiple billing periods | Transaction identity, service event, and reversals |
| Accepted correction absent from the account | Credit note and posting reference |
For a monthly minimum, read the rule carefully.
If an agreement defines a $500 minimum for eligible service charges and those charges total $420, the adjustment would be $80 under that rule. Adding another $500 would require a separate contractual basis.
Other agreements may define separate minimums or additional fixed fees. Apply the actual wording.
8. Assign an Evidence Status to Each Finding
A review becomes easier to act on when uncertainty is visible.
Use these categories in your review worksheet:
| Status | Meaning |
|---|---|
| Supported discrepancy | Pricing and activity records support a calculated difference |
| Needs review | A relevant rule, record, or explanation is missing |
| No discrepancy found | The reviewed charge matches the available evidence |
| Not audited | The charge was outside scope or lacked sufficient data |
Track resolution separately. A supported discrepancy can later be submitted, accepted, credited, or otherwise resolved.
Also state coverage. List the fee categories reviewed and those left unverified.
If you report the share of charges reviewed, define the denominator and treatment of credits. Transaction count and dollar value measure different kinds of coverage.
9. Prepare a Correction Request
For the full template, evidence packet, and follow-up process, see how to dispute a 3PL invoice.
Create one record per finding containing:
- Invoice number and billing period.
- Transaction ID and source row.
- Service and operational reference.
- Billed quantity, rate, and amount.
- Expected quantity, rate, and amount.
- Calculated difference.
- Pricing-rule reference.
- Supporting operational record.
- Related credits or adjustments.
- Requested action.
For the picking example:
The attached shipment records show 500 additional billable items. The applicable rate-card section lists $0.40 per additional item, producing an expected charge of $200. The invoice bills $250. Please review the $50 difference and confirm whether another pricing rule applies or a correction should be issued.
Follow the billing-query procedure and deadlines stated in your agreement. Record the submission date and retain the evidence provided.
10. Track Corrections Until They Are Reconciled
Use a resolution sequence:
Submitted → Provider response → Accepted or explained → Correction posted → Reconciled
For an accepted correction, verify the credit note, revised invoice, account adjustment, or refund.
Keep these amounts separate:
- Potential discrepancies under review.
- Corrections accepted by the provider.
- Credits posted to the account.
- Cash refunds received.
This prevents an accepted request from being counted as money received.
If a credit is applied to a later invoice, retain both references so the resolution can be traced.
3PL Invoice Audit Checklist
Use this checklist when reviewing an invoice:
Frequently Asked Questions
Can I audit a 3PL invoice in a spreadsheet?
Yes. A spreadsheet can organize transactions, calculate expected charges, and track findings.
It works well for a manageable review. As transaction counts and pricing exceptions grow, maintaining source references and applicable rate versions can become time-consuming. Keep formulas, assumptions, and original records traceable.
Does a repeated charge prove duplicate billing?
A repeated charge is a reason to investigate. Check whether it represents another package, service event, or adjustment, and confirm that overlapping exports have not duplicated the row.
What if I do not have the rate card?
You can reconcile totals and identify charges requiring explanation. Request the applicable pricing terms before calculating contractual differences.
Should I compare the invoice with advertised pricing?
Advertised pricing helps explain general fee structures. Your applicable account agreement provides the basis for verifying charges.
How often should I review invoices?
A practical starting point is each billing cycle, with extra attention after rate changes, warehouse moves, or changes in fulfillment activity. Schedule the review within your agreement’s billing-query deadlines.
What if some charges cannot be verified?
Mark them as “needs review” or “not audited,” depending on the reason. Record the missing evidence and identify the next step needed to complete the check.
Put the Evidence to Work
Choose an invoice with accessible billing detail and a fee category with clear pricing. Verify its quantities and rates, then expand the review to storage, shipping, and additional services as supporting records become available.
A useful finding lets another person follow the same records and reproduce the result.
The planned workspace will guide a supported invoice review from uploaded source files to an evidence-linked report. Customer processing is not open yet.
Bring the invoice, applicable pricing terms, and details of the operational exports you can provide. Agree on the scope before sharing sensitive files. Do not send invoice, contract, or customer files by email.
Guides in This Series
- How to Audit a 3PL Invoice: A Practical Checklist
- Duplicate 3PL Charges: How to Find and Verify Them
- How to Calculate 3PL Storage Fees and Check Your Invoice
- How to Dispute a 3PL Invoice With Clear Evidence
- 3PL Fulfillment Fees: How to Check Your Invoice
- 3PL Receiving Fees: How to Check Your Invoice